Why the board said no to the 2021 merger
The question that settled it was not about price. It was about who would be sitting at the kitchen table afterward.
In the spring of 2021 a national bank approached Meridian Trust with an offer to buy it. The price was generous — generous enough that every shareholder, including the eleven founding families' descendants and the staff who hold shares through the employee plan, would have been comfortable. The board took three months to answer. This is an account of how we reached the answer, because I think the method matters more than the result.
The first thing we did was refuse to decide quickly. There is a rhythm to acquisition offers that favours the buyer: the offer arrives with a deadline, the deadline creates urgency, and urgency narrows the question to price. We wrote to the acquirer that the board would respond in ninety days and that no one at the bank would discuss terms before then. They were surprised. They waited.
The second thing we did was to go to the branches. I had sat on this board for six years, and I realised I could not say with confidence what a teller in Bend thought the bank was for. So the directors held open meetings with the staff at all three branches — no management present, no agenda, one question: what would change for your customers if we were part of a bank forty times our size? The answers were specific. A Salem banker described a hazelnut grower whose seven-year orchard loan would not exist in a bank with a standard products list. A Bend teller described the Second Chance Checking customers who would be screened out by an automated system in Charlotte. Nobody talked about their jobs. They talked about their customers.
The third thing we did was to put the money on the table honestly. Our CFO, Priya Venkataraman, built the comparison without mercy: what the shareholders would receive, what the bank's standalone value was likely to be in five and ten years, and the probability that we would be made a less generous offer later, from a weaker position. The board needed to know that saying no had a price, in dollars, and roughly what it was. It did. We said so in the minutes.
Then I asked the question that settled it. Daniel Reyes, our chief executive, tells a story about his parents' bakery, which nearly lost its lease in 1988 and was saved by a loan officer who came to the family's kitchen table three evenings in a row. The bank that employed that officer no longer exists; it was acquired in 1996 and the branch closed in 1999. So I asked the board: who would the loan officer be, afterward, for the family at the kitchen table? Not in the first year, when the acquirer would keep every promise. In the sixth year, when the people who made the promises had moved on.
No one could name that person. That was the answer. The vote was nine to nothing, and we have repeated it every autumn since, whether or not anyone is offering. Independence is not a condition a bank is in. It is a decision a board makes, again, every time it is asked, and a decision ought to be made on purpose, in writing, with names attached.
I spent eighteen years as an appellate judge and most of what I learned there applies to a boardroom. Decide slowly. Hear from the people the decision will land on. Write down the cost of each path before you choose one. And when the question in front of you is complicated, look for the simpler question underneath it. Ours was: whose bank is this for? We knew the answer. We just had to be asked.
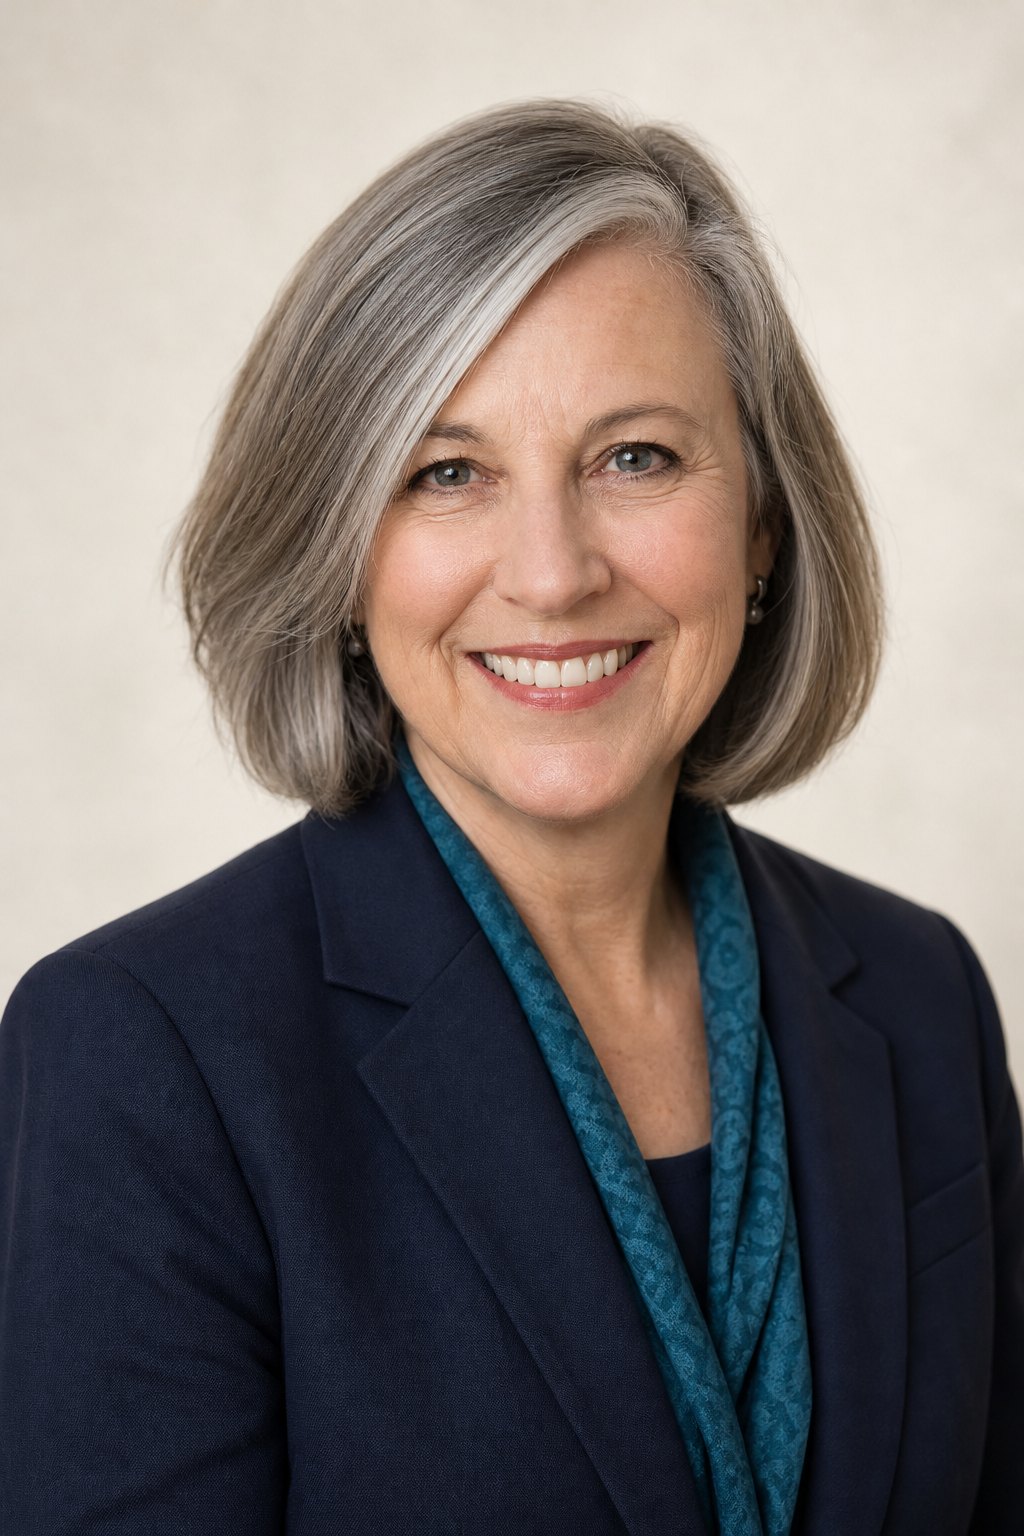
Served eighteen years on the Oregon Court of Appeals. Has chaired the board since 2020 and reads every page of every board packet.
More from Inkwell
What a community bank should do when a customer's business is in trouble — Daniel Reyes
You should never have to guess what you're paying for — Hannah Weiss
How to read an annuity contract — James Whitfield